Protect Your Rental Property With the Right Insurance.
Renting out a home is different from living in it. Your insurance should be designed around that difference.
If you own a home that is rented to tenants, it is important to make sure the property is insured under the right type of policy. A standard homeowners policy is generally intended for an owner-occupied residence and may not be appropriate for a rental property.
Do You Own a Home You Rent to Someone Else?
Whether you own one rental property or are building an investment portfolio, having the right insurance matters.
Landlord insurance is designed with the unique risks of rental properties in mind, including tenant occupancy and the different exposures that come with renting a home.
The Type of Policy Matters
A homeowners policy is generally designed for a home where the insured owner lives. If a property is not owner occupied and is instead being rented to tenants, the property may need a landlord or dwelling policy designed for rental use.
Insuring a rental property under an inappropriate policy can create serious coverage issues. Depending on the policy terms and circumstances of a loss, a claim could be limited or denied if the actual occupancy or use of the property does not match the policy.
That's why it's important to tell your insurance professional how the property is actually being used.
What's the Difference?
The type of policy you need depends in part on whether you live in the home or rent it to someone else.
Homeowners Insurance
Owner Occupied
- Designed for an owner-occupied residence
- Based on the owner living in the home
- Designed around personal residential risks
- May not provide the coverage appropriate for a rental property
Landlord Insurance
Rental Property
- Designed for rental and investment properties
- Accounts for tenant occupancy
- Designed around rental-property risks
- Can help protect your investment and rental income
Landlord Insurance Coverage
Depending on the policy and options selected, landlord insurance can address several important risks associated with owning a rental property.
Property Protection
Coverage can help protect the rental dwelling against covered losses, subject to the terms, conditions, limits and exclusions of the policy.
Liability Protection
Rental properties can create additional liability exposures. The appropriate policy can provide liability protection for covered claims, subject to policy terms.
Rental Income
Depending on the policy, coverage may be available for certain lost rental income following a covered loss.
Other Structures
Detached structures associated with the rental property may be eligible for coverage depending on the policy selected.
Personal Property
Landlords may have appliances, furnishings or other property at the rental. Coverage depends on the policy and property involved.
Customized Protection
Every rental property is different. Occupancy, property type, location and selected coverage can all affect the policy that is appropriate.
Rental Property Risks Are Different
Tenant Occupancy
You may not live at the property, and the people occupying the home may change over time. The policy needs to account for that exposure.
Property Maintenance
Landlords remain responsible for maintaining the property even when someone else lives there. Maintenance and liability exposures should be considered.
Lost Rental Income
A covered loss could potentially prevent tenants from occupying the property. Depending on the policy, coverage may be available for qualifying lost rental income.
Liability Exposure
Owning property that someone else occupies creates risks that may differ from those associated with your own residence.
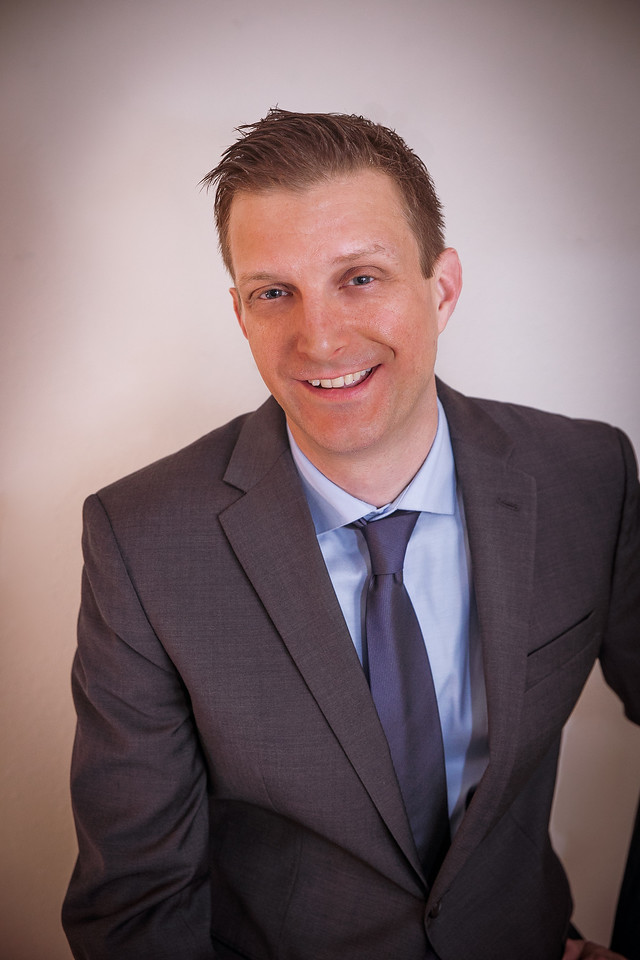
Let's Make Sure Your Rental Is Properly Insured.
I'm Richard Bunkley, owner of Bunkley Insurance Group in Austin, Texas. I help homeowners and property owners evaluate their insurance needs and understand the differences between the policies available to them.
I've earned Allstate's Elite Agency distinction, have been recognized with Honor Ring four times and have achieved Pinnacle Elite recognition. I also hold a BAAS degree from Texas State University and an MBA from Baylor University.
If you own a rental property, I'd be happy to review how the property is being used and help you determine what type of insurance may be appropriate.
Common Questions About Rental Property Insurance
Do I need landlord insurance if I rent out my house?
If you own a home that you rent to tenants, you generally need a policy designed for rental-property use rather than a standard owner-occupied homeowners policy. The appropriate policy depends on the property, occupancy and coverage selected.
Can I use my homeowners insurance for a rental property?
A standard homeowners policy is generally designed for an owner-occupied residence. If the home is being rented to tenants, the policy may not be appropriate. Failing to disclose the property's actual use can create significant coverage issues in the event of a claim.
Does landlord insurance cover the tenant's belongings?
Generally, the landlord's policy is intended to protect the landlord's covered property and liability interests rather than the tenant's personal belongings. Tenants should consider renters insurance for their own possessions and liability needs.
Can landlord insurance cover lost rent?
Some landlord policies may provide coverage for qualifying lost rental income following a covered loss. Whether coverage applies depends on the policy terms, limits, exclusions and circumstances of the loss.
What information is needed for a landlord insurance quote?
Information such as the property's location, age, construction, occupancy, condition, number of units, rental arrangement and desired coverage can help determine the appropriate policy and available options.
What if I only rent my home occasionally?
The appropriate insurance can depend on how frequently the property is rented, how it is rented and how the property is otherwise used. It is important to discuss the actual use of the property with your insurance professional before selecting coverage.
Policy details, coverage options, availability, eligibility, limits, exclusions, and pricing may vary based on the product, carrier, individual circumstances, and coverages selected at the time of sale. Information on this website is provided for general educational and informational purposes only and is not intended to provide specific coverage advice or create a contract of insurance. Coverage is subject to the terms, conditions, limitations, exclusions, and other provisions of the applicable policy. Please review your policy documents and consult with your insurance professional regarding your specific situation.